Appraisal is supposed to resolve disputes, not create new ones. Yet anyone who has been around property insurance appraisal long enough knows that an unclear appraisal award can generate a second dispute over what the appraisers actually decided.
The recent decision in Jamestown Villas Homeowners Association v. State Farm Fire and Casualty Company 1 presents an interesting question: when an appraisal award contains a dollar figure that seems clear, should a court ever ask the appraisers what they meant? The federal appellate court’s answer was essentially no.
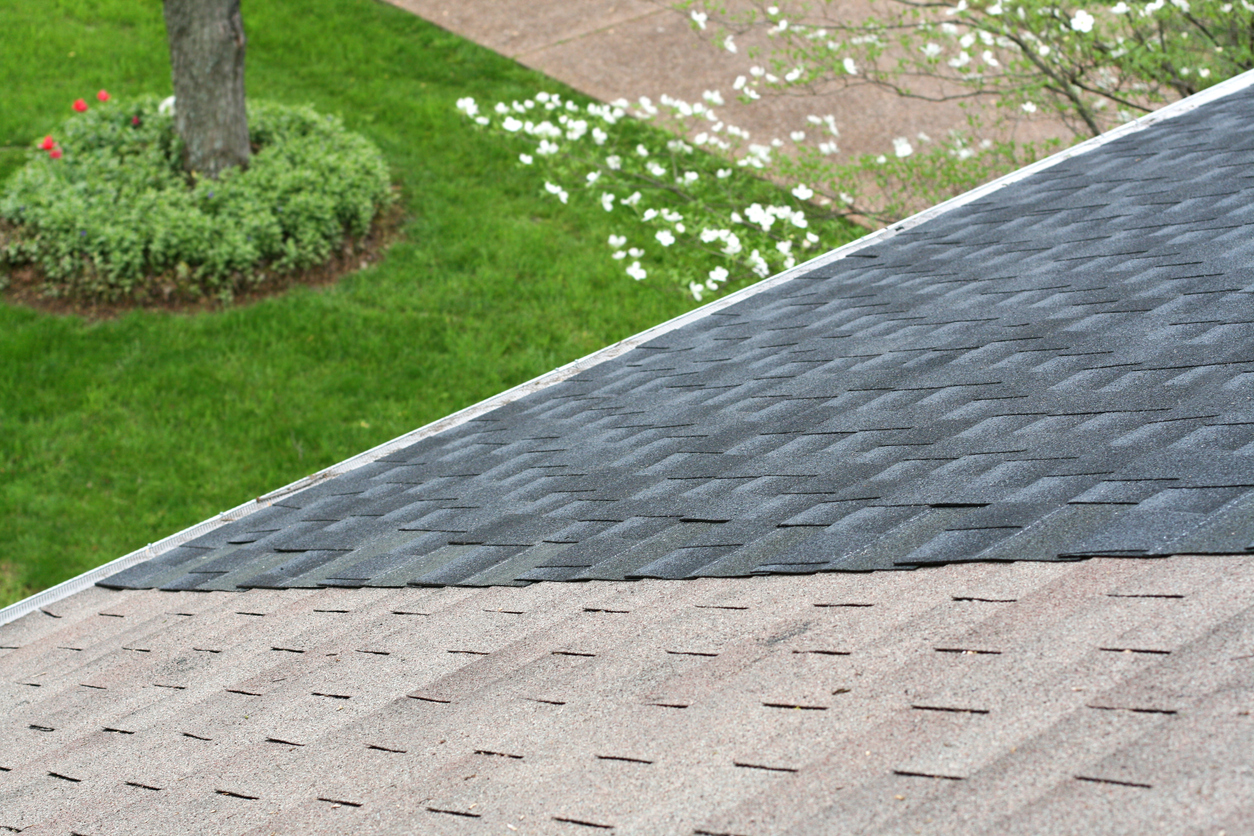
The dispute arose after hail damaged the roofs of nine condominium buildings in Minnesota. Most of the damage involved valley metal where two sloped roof sections meet. Replacing the damaged metal necessarily required removing some of the surrounding shingles. Everyone agreed the hail damage was covered. The fight was over whether replacement shingles were available that were of “like kind and quality” to those already on the roofs.
The matching issue produced a very large difference in dollars. If the proposed replacement shingles sufficiently matched, State Farm could repair the valley areas and replace only the adjoining shingles. If they did not, the Association contended that the roofs had to be replaced. The appraisal panel ultimately awarded $52,482.81 as replacement cost value. A full reroof would have cost approximately $742,163.80. So far, this sounds like a fairly ordinary appraisal dispute.
The appraisal panel had been asked questions about the replacement shingles. It answered “yes” when asked whether the bundled shingles had a reasonably uniform appearance compared with the existing shingles. But the panel also answered “no” when asked whether shingles from the same replacement product that had actually been installed during a partial repair had a reasonably uniform appearance. The replacement shingles sitting in bundles matched, but those same shingles did not match once installed.
The federal district judge understandably wanted to know what the appraisal panel meant. The court initially found the award ambiguous and sent questions back to the panel for clarification. State Farm even sought reconsideration of that ruling, arguing in part that the court lacked authority to seek clarification. The district judge declined to reconsider the ruling.
After receiving the clarification, the district court eventually entered summary judgment for State Farm. The clarification established that two panel members believed the proposed replacement shingles constituted an acceptable match. The district court treated that factual determination as one committed to the appraisal panel and confirmed the award.
The appellate court affirmed State Farm’s victory but took a much more restrictive view of what the district judge should have done. According to the appellate court, nobody needed to ask the appraisers anything. The number itself told the story.
The panel awarded approximately $52,000 rather than approximately $742,000. From that number, the court reasoned that the panel necessarily determined the proposed replacement shingles were sufficiently “like kind and quality.” Otherwise, the panel would have awarded the amount necessary for replacement of the roofs. In other words, the dollar amount answered the matching question.
The court emphasized Minnesota’s strong presumption in favor of the validity of appraisal awards. It also relied upon longstanding Minnesota law restricting the use of appraiser testimony to explain or alter an otherwise clear award. Once the court determined that the $52,482.81 award necessarily reflected a finding that the shingles adequately matched, the inquiry was essentially over.
The panel’s determination concerning reasonable color matching was a factual matter incidental to determining the amount of loss. Under Minnesota law, those factual determinations are for the appraisal panel rather than a court to reconsider simply because one party believes the panel got them wrong.
One part of the opinion, at the bottom of the page, caught my attention and is the reason for the word “ever” in the title of this blog. In a footnote, the appellate court said the case “should have been over at the start.” Because the award was not ambiguous, the district court should never have sent clarification questions back to the appraisers. The subsequent clarification ultimately made no difference because the district court confirmed the award anyway.
There is a lot of practical wisdom in the concept of appraisal finality. Nobody wants every appraisal followed by depositions of the appraisers asking why they agreed with one item, rejected another, or arrived at a particular number. If appraisal simply becomes another stage of litigation, one of its principal purposes is lost.
But I am not convinced the issue in Jamestown Villas is quite that simple. There is a difference between asking an appraiser months later to explain the private reasoning behind a perfectly clear award and trying to understand contradictory written findings made as part of the appraisal process itself.
Here, the trial judge did not create the ambiguity. The appraisal panel did. The panel seemingly said that the replacement shingles provided a reasonably uniform appearance before installation but did not provide one after installation. Those answers concerned the very factual issue that separated a roughly $52,000 repair from a roughly $742,000 replacement.
The appellate court resolved that problem by working backward from the number. Since the panel awarded $52,482.81, the panel must have found the shingles acceptable. Since the number reveals what the panel must have found, the award was not ambiguous. Since the award was not ambiguous, the court should never have asked for clarification.
The court’s reasoning has an appealing simplicity. It also risks becoming circular. Suppose an appraisal award expressly contains factual findings that point in two different directions. Should courts disregard those findings whenever the dollar amount permits a judge to infer which finding the panel must have intended to control?
The most practical lesson from Jamestown Villas is one I have repeatedly emphasized when teaching appraisal. Panels need clear awards. This case also sends a warning to policyholders and insurers alike. Don’t assume you can clean up an unclear appraisal afterward. A court may decide that the number itself supplies all the explanation anybody is entitled to receive. Getting the appraisal award right the first time is important.
My friend and frequent appraisal debating partner, Steve Badger, has complained many times about abuses in the appraisal process. On the fundamental purpose of appraisal, however, Steve and I actually agree far more than some might suspect. Badger once said:
“Sadly, these abuses are ruining a process that was intended to help policyholders promptly resolve disputed claims without the need for litigation.”
He is right about the purpose. The challenge is making certain that finality does not become a substitute for clarity.
Thought For The Day
“Sadly, these abuses are ruining a process that was intended to help policyholders promptly resolve disputed claims without the need for litigation.”
—Steve Badger
1 Jamestown Villas Homeowners Ass’n v. State Farm Fire and Cas. Co., No. 25-3154 (8th Cir. Sept. 4, 2026).